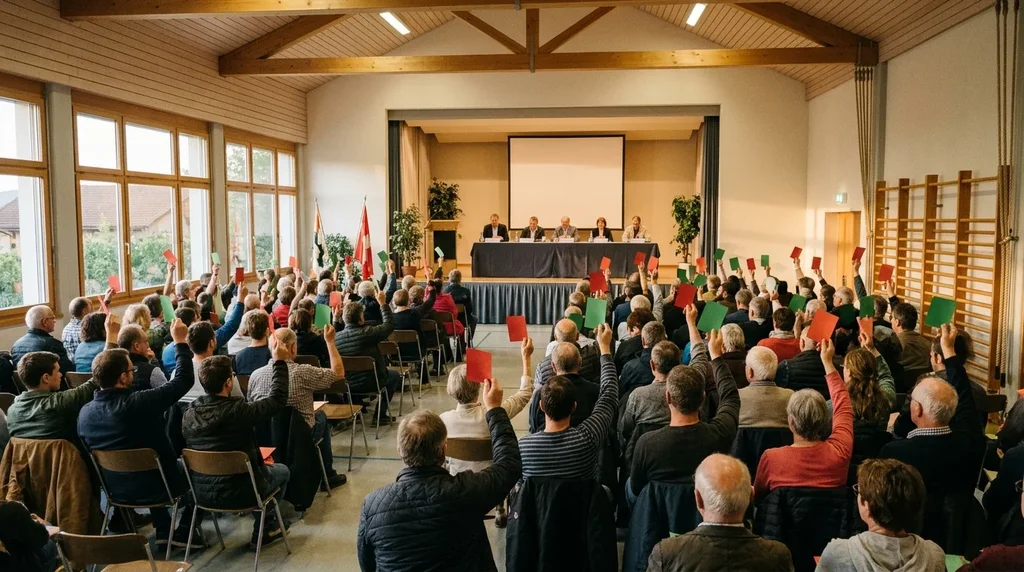
Raiffeisen, a Swiss cooperative banking group, is one of the three banks that the Swiss Financial Market Supervisory Authority (FINMA) classifies as domestically focused systemically important banks, alongside Zürcher Kantonalbank (ZKB) and PostFinance. For a Raiffeisen client or cooperative member, this status requires the group to submit an emergency plan every year, which FINMA judged compliant on October 14, 2026. Raiffeisen is also the second most frequently cited main bank among Swiss people, according to a study published in October 2026.
A comparison with the cantonal institutions, their weight and their clientele, can be found on our page on the cantonal bank. Other topics from the sector are gathered in the Banks and FINMA section.
How is the Raiffeisen Group organized?
The group presents itself on two levels: a national entity and local banks. The raiffeisen.ch website is published by Raiffeisen Switzerland, based in St. Gallen, which uses it to share the group's analyses and guides.
Clients, for their part, are directed to "their local bank," which they choose by postcode, by location or by geolocation, with its opening hours, its branches and its ATMs. The banking relationship therefore runs first through the local level, under a common brand.
The offering that is highlighted is that of a retail bank. The Raiffeisen Switzerland homepage, consulted on October 30, 2026, offers to open an account, compare mortgage rates, invest in gold and address retirement provision.
The sources consulted for this article do not detail the core of the cooperative model. They give neither the number of local banks, nor the number of cooperative members, nor the price of a share certificate, nor the voting rights attached to it. These points can be checked with one's local bank.
How much weight does Raiffeisen carry in Switzerland?
Raiffeisen is the second most frequently cited main bank among Swiss people. According to a study by the Lucerne University of Applied Sciences and Arts (HSLU), reported by finews.ch on October 26, 2026, 25% of respondents name it as their main bank. The cantonal banks come first with 28%, ahead of PostFinance (19%) and UBS (17%). These four groups together account for 89% of main banking relationships.
The survey was conducted online by the Bilendi institute, from May 29 to June 11, 2026, among 2,016 people. The gap with the cantonal banks is only three points. The finews.ch headline, "Kantonalbanken überholen Raiffeisen" (cantonal banks overtake Raiffeisen), suggests a change in ranking. However, Raiffeisen's share two years earlier is not published in the sources consulted.
Geography and age widen the gaps. In Ticino, Raiffeisen is the leading main bank with 33%, well ahead of UBS (20%) and the cantonal banks (10%). It also appeals more to young adults than to older people.
| Indicator | Raiffeisen | Point of comparison |
|---|---|---|
| Main bank, all of Switzerland (2026) | 25% | Cantonal banks 28%, PostFinance 19%, UBS 17% |
| Main bank in Ticino (2026) | 33% | UBS 20%, cantonal banks 10% |
| Main bank of 16 to 29-year-olds and 30 to 45-year-olds (2026) | about 27% and 28% | about 21% among older people |
| Rank by assets (2023) | 2nd | UBS 1st, ZKB 3rd, PostFinance 4th |
The ranking varies depending on the measure used. By assets, the 2023 ranking by the agency ADV Ratings, cited by the encyclopedia Wikipedia, places Raiffeisen second, behind UBS and ahead of ZKB. In January 2022, SWI swissinfo.ch described it as the third-largest bank in Switzerland. The two rankings do not cover the same year, and UBS's takeover of Credit Suisse took place in 2023, between the two.
What does systemically important status mean for Raiffeisen?
The status requires Raiffeisen to prepare two documents for FINMA every year. The emergency plan shows how the functions that are systemically important for Switzerland would continue if the bank became insolvent. The recovery plan describes how it would recover by its own means in the event of a financial crisis.
The 2026 verdict is positive for Raiffeisen. According to FINMA's press release of October 14, 2026, its emergency plan meets the regulatory requirements, as does ZKB's. PostFinance's "does not yet meet all the requirements." The recovery plans of all three banks were approved once again. The assessment concerns documents submitted in 2025, detailed in our article on the emergency plans of systemically important banks.
FINMA itself sets out the limit. A compliant plan "does not mean that the continuity of systemically important functions is fully ensured in every conceivable crisis scenario." The authority points out that the requirements applicable to domestically focused banks provide for a lower loss-absorbing capacity than for global systemically important banks. In particularly severe crises, this can restrict the options.
The requirements were tightened after the Credit Suisse crisis: an annual stress test of escalation procedures is now required. According to FINMA, the annual crisis exercises still need to be documented and the crisis communication plans updated, among other things.
Does the "too big to fail" reform concern Raiffeisen?
Part of the reform targets all systemically important banks, and therefore Raiffeisen. The Federal Council presented measures on April 22 and then on August 12, 2026, the date on which it opened a consultation on the Banking Act and the Liquidity Ordinance. These texts remain drafts.
The liquidity component would directly affect the group. According to the Swiss National Bank (SNB) press release of August 12, 2026, the draft ordinance provides that systemically important banks and medium-sized banks prepare enough collateral to obtain liquidity assistance from the central bank. The SNB welcomes these too big to fail measures, as well as those on recovery planning and resolvability. The volume of collateral required has not been quantified.
Raiffeisen client or cooperative member: what protects your money?
The protection of Raiffeisen clients rests on deposit insurance. According to esisuisse, the self-regulatory body of Swiss banks, it covers deposits of up to 100,000 francs per client and per bank in the event of bankruptcy. It applies to individuals and companies alike, and all banks with a branch in Switzerland must be members. A revision of the Banking Act strengthened it as of January 1, 2023.
The broader public guarantee only concerns cantonal institutions. The state guarantee of cantonal banks commits a canton to its own bank. According to Wikipedia, 21 of the 24 cantonal banks have one. Raiffeisen is not among them.
For an SME, the ceiling is the same as for an individual: 100,000 francs. Beyond that, no other guarantee is documented by the sources for Raiffeisen. Nor do the sources say whether this ceiling applies local bank by local bank or to the group as a whole. FINMA publishes on its website the list of all authorized institutions, which is useful for checking a bank's status. This page does not constitute financial advice.
Why do Raiffeisen's analyses matter for households?
Raiffeisen also publishes its own indicators, which should be read by distinguishing observations from forecasts. Its transaction price index, based on prices actually paid, shows a year-on-year increase of 3.6% for single-family homes and 5.9% for apartments in the third quarter of 2026, according to our article on owner-occupied housing prices. On October 8, 2026, the bank raised its forecast for Swiss gross domestic product (GDP) growth in 2026 to 1.7%, from 0.8% previously. It concludes that the SNB could raise its rates, a hypothesis detailed in Raiffeisen's growth forecasts.
Where does the Vincenz case stand?
Pierin Vincenz, former CEO of Raiffeisen, was convicted of fraud in April 2022 by the Zurich District Court, in a judgment that is not final. The Zurich High Court will deliver its appeal verdict on January 11, 2027, according to a Keystone-ATS dispatch. Until then, the presumption of innocence applies, as our article on the Vincenz case and its verdict points out.
Key figures
- 25% of people surveyed in 2026 cite Raiffeisen as their main bank, compared with 28% for the cantonal banks (HSLU study).
- 33% in Ticino, where Raiffeisen is the leading main bank.
- 2nd-largest bank in Switzerland by assets in 2023, behind UBS (ADV Ratings, cited by Wikipedia).
- 3 domestically focused systemically important banks: Raiffeisen, ZKB and PostFinance (FINMA).
- October 14, 2026: FINMA judges Raiffeisen's emergency plan compliant.
- 100,000 francs: ceiling of deposit insurance, per client and per bank (esisuisse).
What we don't know yet
- The number of local banks and cooperative members, the price of a share certificate and the rights attached to it: the sources consulted do not provide them.
- Whether the 100,000-franc deposit insurance ceiling applies to each local bank or to the group as a whole.
- The volume of collateral that the Liquidity Ordinance would require of Raiffeisen, and the date on which the reform would come into force.
- Raiffeisen's share as a main bank two years before the HSLU study.
- The outcome of Pierin Vincenz's appeal, expected on January 11, 2027.
Sources
- Raiffeisen Switzerland: the group's homepage (consulted on October 30, 2026)
- FINMA: the authority's homepage (consulted in October 2026)
- Wikipedia: article "Banque cantonale", ranking of banks by assets in 2023 based on ADV Ratings (consulted in October 2026)
- FINMA: "FINMA assesses the emergency and recovery plans for Zürcher Kantonalbank, Raiffeisen and PostFinance" (October 14, 2026), via 2clics
- Swiss National Bank: "Swiss National Bank welcomes measures to strengthen ‘too big to fail’ regulations" (August 12, 2026), via 2clics
- finews.ch: "Kantonalbanken überholen Raiffeisen – UBS verliert" (October 26, 2026), HSLU study, via 2clics
- esisuisse: Swiss deposit insurance, via 2clics
- SWI swissinfo.ch / Keystone-ATS: Raiffeisen's forecasts (October 8, 2026), transaction price index (October 12, 2026), Vincenz case (October 6, 2026), via 2clics